 HELPLINE:
KEY TAKEAWAY
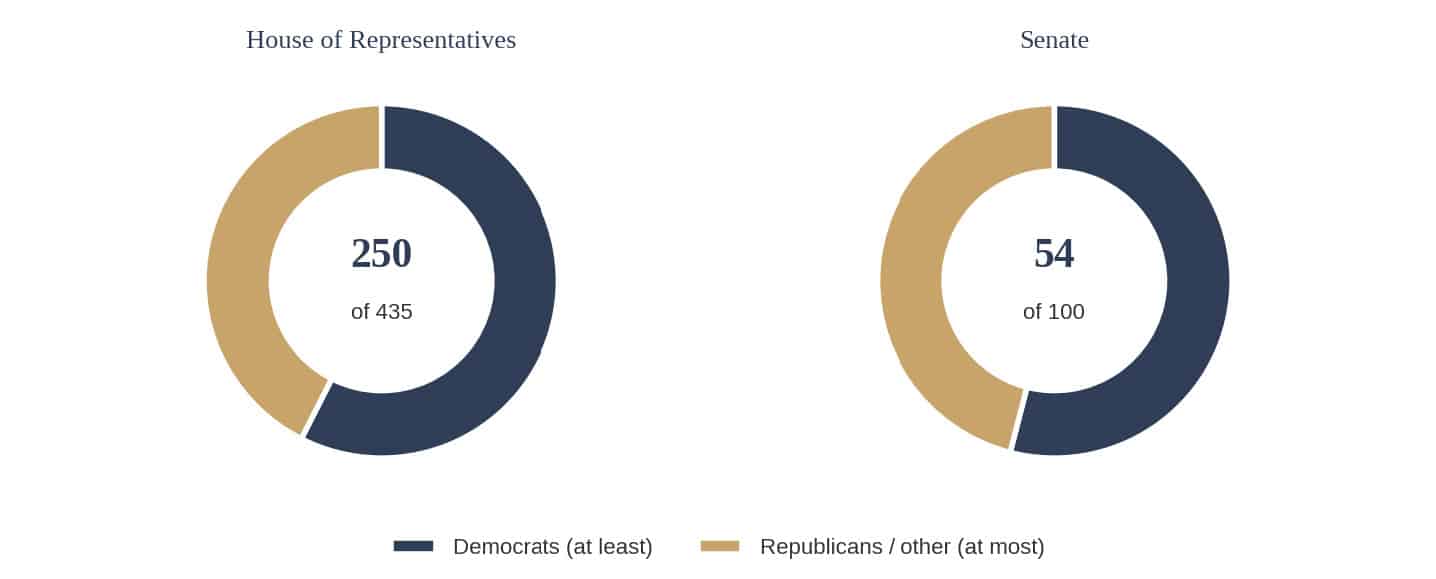
The US midterm result — Democrats taking both chambers — has reset the macro narrative overnight. Hopes of US–Iran de-escalation pulled oil down sharply (WTI −8% on Wednesday), the dollar and yields eased, and gold rose. Equities rallied, but with a clear rotation out of AI-infrastructure names into value, consumer and defensive sectors. The Bank of England is expected to deliver its first hike since 2023 at 12:00 GMT today.
MARKETS & MACRO
Equities
Wall Street rallied on Wednesday after the midterms. The Dow gained about 3% (c. 1,570 points, to 53,356), its best day since April 2025, and the S&P 500 rose 1.6% to around 7,689. Leadership was defensive and consumer-oriented (Walmart +3%); Apple reached a record high, while AI-infrastructure names — Nvidia, AMD, CoreWeave — declined. This morning, futures point to a continued rotation: Nasdaq-100 c. −1.2%, S&P 500 c. −0.3%, Dow c. +0.3% (XTB; NordFX).
Asia split along sector lines. Chip stocks sold off — the Kospi fell c. 4.8% (SK Hynix −9%, Samsung −6.7%), triggering a program-trading halt, and the Nikkei lost 1.5% even as the broader Topix rose 1.4%. China moved the other way: Shanghai +3.6%, Hang Seng +3.0%, Hang Seng Tech +5%. India’s Sensex closed 1.8% higher at 78,690, aided by lower oil (Dynamite News). In London, the FTSE 100 closed 191 points higher at 10,829 on Wednesday, with banks leading, and was indicated higher again this morning (The Market Reporter; LSE.co.uk).
Index moves following the US midterm result
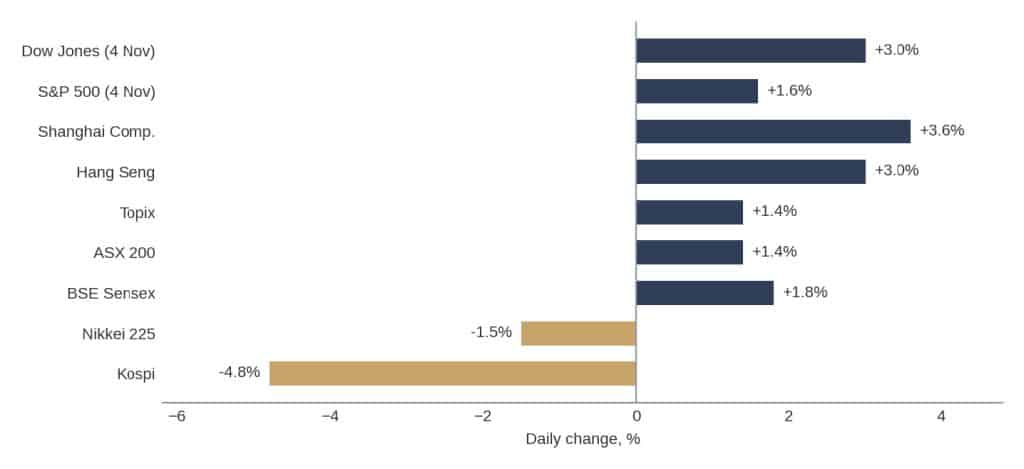
Source: XTB morning report, 5 Nov 2026 (citing exchange data); NordFX; Dynamite News. US figures are Wednesday 4 Nov closes; Asian figures are Thursday 5 Nov session moves. Chart redrawn from reported figures.
Rates and central banks
Bank of England (12:00 GMT today): a 25 bp hike to 4.00% is widely expected — the first since August 2023 — after energy costs lifted UK CPI to 3.5%. Bloomberg’s decision guide frames it as the first hike in three years; the vote split and guidance on further moves will matter most for gilts and sterling. The outcome was not yet published at the time of writing. (Bloomberg; FXStreet)
Elsewhere: BoJ minutes from September (hike to 1.25%) show board support for further tightening; the SNB has acknowledged October inflation (1.5%) surprised it, firming expectations of a December move. US futures still price a high probability of a December Fed hike, though Citi argues a lasting reopening of the Strait of Hormuz could turn the Fed towards cuts. The White House commission’s hearing on Fed Governor Lisa Cook has been postponed to 14 December. US weekly jobless claims are due today and payrolls on Friday (XTB).
FX, commodities and data
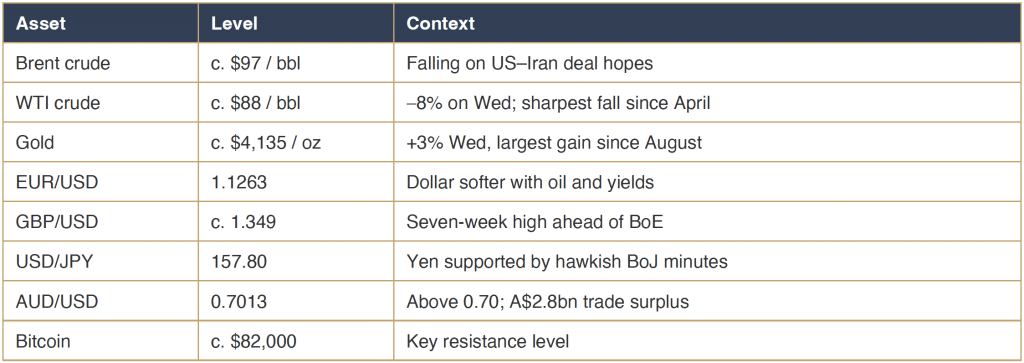
Source: XTB morning report, 5 Nov 2026; Vantage Markets (GBP/USD, pre-decision). Indicative levels, morning of 5 Nov.
European natural gas is up c. 9% on the week, a reminder that the region’s energy squeeze has not eased. Citi’s gold scenario targets $4,500 within three months should lower oil shift the Fed. On data: US ISM services grew at its slowest pace in three months; Japan’s composite PMI hit a five-month low; Indonesia’s Q3 GDP grew 5.47% y/y, ahead of forecasts (XTB).
Corporate notes: Toyota raised full-year operating profit guidance to ¥3.90 trillion and expanded its buyback; Commerzbank held its ≥€3.4bn profit target, below consensus; Qualcomm and Arm both beat but fell after hours on guidance. China has reportedly blocked SoftBank’s $5.4bn purchase of ABB’s robotics unit (Financial Times, via XTB). AstraZeneca has offered c. $10bn for Rhythm Pharmaceuticals, according to the WSJ.
WEALTH & PRIVATE BANKING
Italy: proposed exit tax
Article 17 of Italy’s draft 2027 Budget Bill would tax unrealised gains at 26% when individuals move tax residence abroad, from 1 January 2027. It would apply to those holding €800,000 or more in shares, bonds, funds and other securities who have been resident for at least six of the previous ten years; deferral reportedly requires half the liability up front. It is not yet law — Parliament normally approves the budget by end-December and the article may be amended. It remains unclear whether departing flat-tax residents (now €300,000 a year for new arrivals since 2026) would be caught. Utmost has warned it could weaken Italy’s appeal to internationally mobile families (IMI Daily; WealthBriefing; Il Sole 24 Ore).
Adviser note: clients with Italian residency and cross-border plans may wish to review timelines and portfolio composition with tax counsel before year-end, pending the final text.
United States: policy outlook
A Democratic Congress gains subpoena power, and analysts are already flagging a 2027 debt-ceiling confrontation as the main risk for bond markets (UBS). Separately, Goldman Sachs estimates c. 45% of planned US data-centre capacity sits in states that could tighten regulation after the elections — relevant to concentrated AI-related holdings (XTB).
Industry moves
- A Fort Worth team left UBS with $3.61bn in client assets to launch Cleros Wealth Partners (WealthManagement.com).
- Creative Planning acquired a Syracuse-based RIA overseeing $2.2bn; Kestra’s Bluespring added the $920m Whitaker-Myers Wealth team (WealthManagement.com).
- UBP appointed a UK head of wealth management for client coverage (Global Private Banker).
- The FT Live Global Wealth Management Summit concludes in London today (EventBrowse).
WORLD NEWS
Composition of the new US Congress
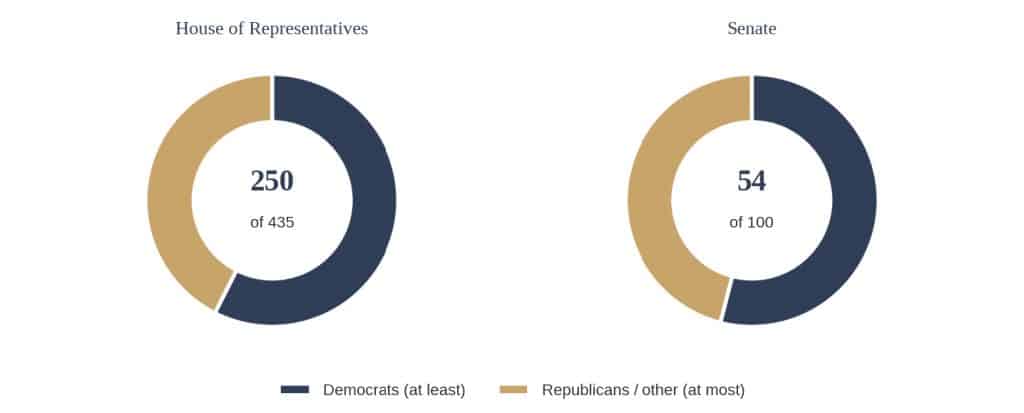
Source: CNBC projections as reported by XTB, 5 Nov 2026 (Democrats hold at least 250 House and 54 Senate seats; counts not final). Chart redrawn from reported figures.
- US midterms. Democrats won both chambers, including in redrawn districts. President Trump struck a conciliatory tone; Vice President Vance attributed the loss to the Iran war. In Texas, Democrat Gina Hinojosa won the governorship and James Talarico the Senate race (XTB).
- Middle East. No US–Iran deal yet; Qatar has stepped up mediation. The IRGC reported tanker fires and a mine strike in the Strait of Hormuz — not independently confirmed (XTB; CBS News).
- Spain. A collision between two high-speed trains in central Spain has left at least 68 dead, with protests in Madrid (CBS News).
- Europe – security. Cyberattacks have hit French blood banks after hackers remotely took over supermarket refrigeration across Europe; false bomb threats are disrupting flights (Global News).
- Ukraine. The death toll from Russian strikes on the Zaporizhzhia region has risen to 24 (CBS News).
- Israel. Coalition talks continue; the next prime minister remains undecided (CBS News).
SOURCES
XTB — What Drives the Market, 5 Nov 2026:
https://www.xtb.com/int/market-analysis/news-and-research/what-drives-the-market-top-morning-news-november-5-2026
Bloomberg — BOE poised for first rate hike in three years:
https://www.bloomberg.com/news/articles/2026-11-05/boe-poised-for-first-rate-hike-in-three-years-decision-guide
FXStreet — BoE expected to hike to 4.00%: https://www.fxstreet.com/news/boe-expected-to-hike-interest-rate-to-400-202611050700
NordFX — Market Pulse, 5 Nov 2026: https://nordfx.com/market-news/market-pulse-november-05-2026
IMI Daily — Italy budget bill proposes 26% exit tax:
https://www.imidaily.com/europe/italy-budget-bill-proposes-26-exit-tax-on-residents-leaving-with-e800000-or-more/
WealthBriefing — Italy’s proposed exit tax (Utmost): https://www.wealthbriefing.com/
WealthManagement.com — Latest news: https://www.wealthmanagement.com/latest-news Global Private Banker: https://globalprivatebanker.net/
CBS News — World: https://www.cbsnews.com/world/
Global News — World: https://globalnews.ca/world/
This briefing is for information only and does not constitute investment, tax or legal advice. Market levels are indicative and drawn from third-party reports published on the morning of 5 November 2026; figures may be revised.